Fintech Trends Reshaping US Banking by 2026
The financial services industry in the United States is currently experiencing a period of unprecedented transformation, driven largely by the rapid evolution of financial technology, or fintech. As we look towards 2026, the landscape of banking and finance will be almost unrecognizable from what it is today, thanks to a confluence of innovative technologies and shifting consumer expectations. This article will delve deep into the three most significant fintech trends banking is embracing, exploring how artificial intelligence (AI), embedded finance, and blockchain technology are not just buzzwords, but foundational pillars reshaping the future of financial services in the US.
The pace of change is accelerating, and financial institutions that fail to adapt risk being left behind in a fiercely competitive market. From enhancing efficiency and security to personalizing customer experiences and democratizing access to financial tools, these fintech trends banking innovations are poised to redefine how money moves, how decisions are made, and how value is created. Understanding these trends is crucial for anyone involved in the financial sector, from established banks and credit unions to burgeoning fintech startups and, of course, the end consumer.
The AI Revolution: Intelligent Automation and Hyper-Personalization in US Banking
Artificial Intelligence (AI) is arguably the most transformative of all fintech trends banking is currently grappling with. Its impact is pervasive, touching almost every facet of financial operations, from back-office processes to customer-facing interactions. By 2026, AI will no longer be a nascent technology but an indispensable component of successful financial institutions.
Enhanced Efficiency Through Automation
One of the most immediate benefits of AI in banking is its ability to automate repetitive, rules-based tasks. This includes everything from fraud detection and anti-money laundering (AML) compliance to loan application processing and customer service inquiries. AI-powered algorithms can sift through vast quantities of data at speeds and accuracies far beyond human capabilities, drastically reducing operational costs and improving efficiency.
- Fraud Detection: AI systems can analyze transactional patterns in real-time, identifying anomalies that might indicate fraudulent activity with incredible precision, significantly reducing financial losses for both banks and their customers.
- Compliance and Regulation: Navigating the complex web of financial regulations is a significant burden for banks. AI can automate the monitoring of transactions and customer behavior to ensure compliance with AML, KYC (Know Your Customer), and other regulatory requirements, minimizing risks and penalties.
- Credit Scoring and Loan Underwriting: Traditional credit scoring models are often rigid. AI can leverage a broader range of data points, including non-traditional data, to provide more nuanced and accurate credit assessments, opening up access to credit for underserved populations while managing risk effectively for lenders.
Hyper-Personalization and Customer Experience
Beyond efficiency, AI is revolutionizing the customer experience by enabling hyper-personalization. In an increasingly competitive market, banks must offer more than just basic financial products; they must provide tailored advice, proactive solutions, and seamless interactions. This is where AI shines, making it one of the most exciting fintech trends banking is leveraging.
- Personalized Financial Advice: AI-powered chatbots and virtual assistants can offer personalized financial advice, helping customers manage their budgets, save for goals, and even make investment decisions based on their individual financial profiles and risk tolerance. This moves banking from transactional to advisory.
- Proactive Product Recommendations: By analyzing customer spending habits, life events, and financial goals, AI can proactively recommend relevant products and services, such as mortgage refinancing opportunities, investment products, or tailored insurance policies, at precisely the right moment.
- Seamless Customer Support: AI-driven chatbots and natural language processing (NLP) are transforming customer service, providing instant, 24/7 support for common queries, freeing up human agents to handle more complex issues. This improves customer satisfaction and reduces wait times.
The ethical implications and responsible deployment of AI are critical considerations. Banks must ensure transparency, fairness, and data privacy as they integrate these powerful tools. However, the benefits in terms of efficiency, risk management, and customer satisfaction are undeniable, solidifying AI’s position as a cornerstone of future fintech trends banking strategies.
Embedded Finance: Banking Becomes Invisible
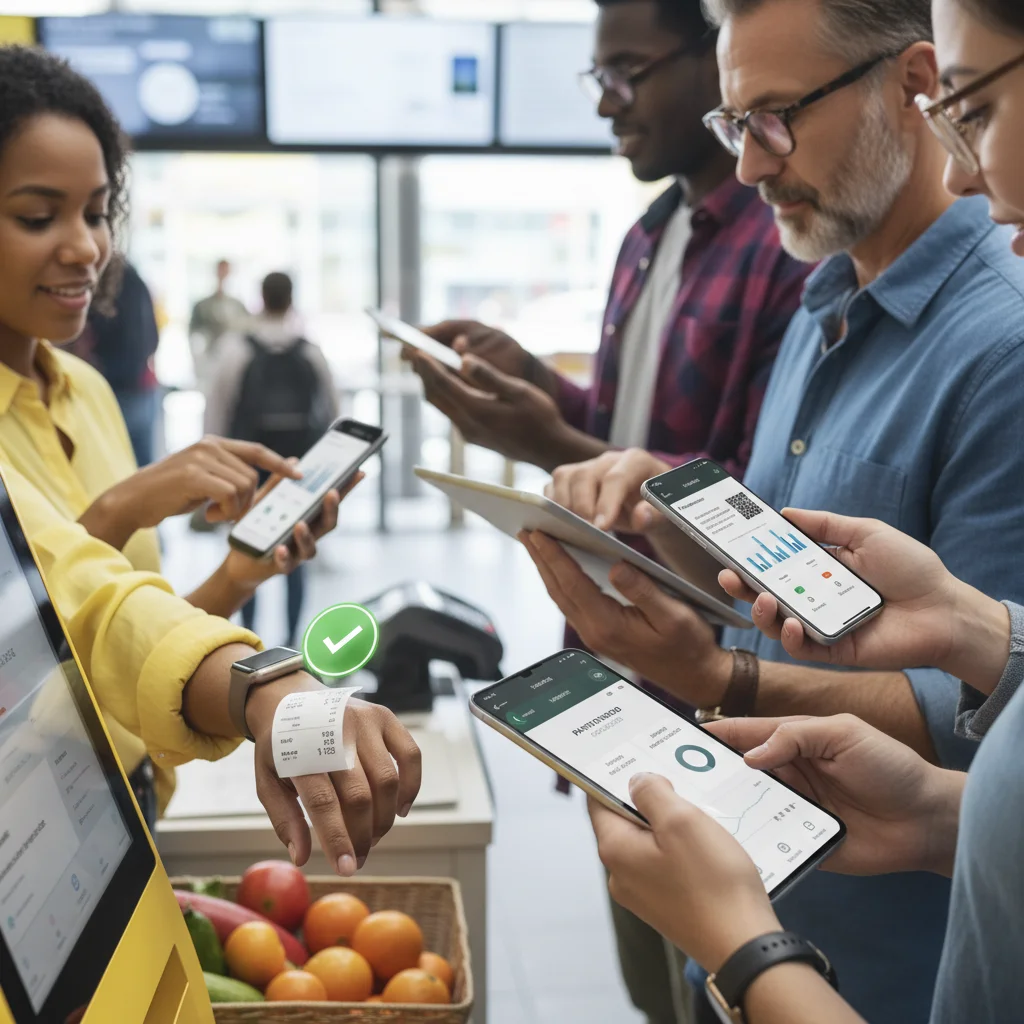
Another transformative force among fintech trends banking is embedded finance. This concept refers to the seamless integration of financial services directly into non-financial platforms and ecosystems. Instead of customers actively seeking out banking services, these services become an invisible, integral part of their everyday activities, purchases, and business operations. By 2026, embedded finance will have normalized the idea of banking as a utility, accessible at the point of need rather than a separate destination.
Convenience at the Core
The primary driver behind embedded finance is convenience. Consumers and businesses increasingly expect frictionless experiences. Why navigate away from an e-commerce site to arrange financing for a purchase when the option can be presented directly during checkout? Why switch apps to pay for a ride when the payment can be processed automatically within the ride-sharing application itself?
- Point-of-Sale Lending: Retailers are offering instant loans or ‘buy now, pay later’ (BNPL) options directly at checkout, transforming how consumers finance purchases. This is a prime example of embedded credit.
- Insurance in Context: Imagine purchasing travel insurance directly when booking a flight or device insurance when buying a new smartphone, all without leaving the primary platform.
- Payments within Apps: Ride-sharing, food delivery, and even social media platforms now incorporate payment functionalities, making transactions effortless and part of the user journey.
New Revenue Streams and Ecosystems
For non-financial companies, embedded finance represents a significant opportunity to create new revenue streams, deepen customer relationships, and expand their ecosystem. By offering financial services, they become more indispensable to their users. For banks, it means reaching customers in novel ways and partnering with diverse businesses.
- B2B Embedded Finance: Beyond consumer applications, embedded finance is gaining traction in the business-to-business (B2B) space. Supply chain financing, integrated invoicing, and payroll services are being embedded into enterprise resource planning (ERP) systems and business software, streamlining operations for companies.
- Banking-as-a-Service (BaaS): The rise of BaaS is a critical enabler of embedded finance. BaaS platforms allow non-financial companies to integrate banking products and services via APIs (Application Programming Interfaces) without needing to build their own financial infrastructure or obtain banking licenses. This democratizes access to financial capabilities.
The implications for traditional banks are profound. They must decide whether to be providers of BaaS infrastructure, partners in embedded ecosystems, or risk disintermediation as other companies capture customer relationships. This fundamental shift makes embedded finance a pivotal element of future fintech trends banking strategies.
Blockchain Technology: The Foundation of Trust and Transparency
While often associated with cryptocurrencies, blockchain technology’s potential extends far beyond digital currencies and is rapidly becoming a cornerstone of secure and transparent financial operations. By 2026, blockchain will be instrumental in reshaping how transactions are verified, assets are managed, and trust is established in the US financial ecosystem, making it one of the most impactful fintech trends banking is exploring.
Streamlining Cross-Border Payments
One of the most immediate and impactful applications of blockchain in banking is in cross-border payments. Traditional international transfers are often slow, expensive, and opaque, involving multiple intermediaries. Blockchain-based solutions offer a faster, cheaper, and more transparent alternative.
- Real-Time Settlements: Blockchain networks can facilitate near real-time settlement of international transactions, significantly reducing the time it takes for funds to clear.
- Reduced Costs: By eliminating intermediaries and streamlining processes, blockchain can lower transaction fees for cross-border payments, benefiting both individuals sending remittances and businesses engaging in international trade.
- Increased Transparency: The immutable ledger of a blockchain provides a clear, auditable trail of every transaction, enhancing transparency and reducing the potential for errors or fraud.
Digital Assets and Tokenization
The tokenization of real-world assets is another significant area where blockchain is poised to make a massive impact. Tokenization involves representing ownership rights to a physical or digital asset as a digital token on a blockchain. This process can unlock liquidity, enable fractional ownership, and streamline asset management.
- Fractional Ownership: High-value assets like real estate, art, or private equity can be tokenized, allowing for fractional ownership and making investments accessible to a broader range of investors who might not be able to afford the entire asset.
- Increased Liquidity: Tokenized assets can be traded on digital exchanges 24/7, potentially increasing their liquidity compared to traditional markets.
- Supply Chain Finance and Trade Finance: Blockchain can bring unprecedented transparency and efficiency to complex supply chains and trade finance operations, reducing fraud and speeding up transactions by providing a single, shared source of truth for all participants.
Smart Contracts and Automated Processes
Smart contracts, self-executing contracts with the terms of the agreement directly written into code, are a powerful application of blockchain. These contracts automatically execute when predefined conditions are met, eliminating the need for intermediaries and reducing the risk of disputes.
- Automated Loan Agreements: Smart contracts could automate the disbursement of loan funds once collateral is verified or automatically adjust interest rates based on market conditions.
- Insurance Claims Processing: In insurance, smart contracts could automatically process and pay out claims when specific, verifiable events occur (e.g., flight delays, weather events), significantly speeding up the claims process.
While regulatory clarity and scalability remain challenges, the inherent security, transparency, and efficiency of blockchain technology position it as a critical enabler for many future fintech trends banking will incorporate. Its ability to create trust in a trustless environment makes it invaluable for the financial sector.
The Convergence of Fintech Trends: A Holistic Transformation
It’s important to recognize that these three fintech trends banking is currently navigating are not isolated phenomena. Instead, they are deeply interconnected and mutually reinforcing, contributing to a holistic transformation of the financial services industry. For instance, AI can enhance the fraud detection capabilities within an embedded finance solution, while blockchain can provide the secure and transparent ledger for the transactions facilitated by both AI and embedded finance.
Synergies in Action
Consider a scenario where a customer is purchasing a car online. Through embedded finance, they are offered an instant loan. AI algorithms rapidly assess their creditworthiness using a broader range of data, providing a personalized interest rate. The loan agreement itself could be a smart contract on a blockchain, ensuring all parties adhere to the terms and automating future payments. This integrated experience exemplifies the power of converging fintech trends banking is embracing.
Another example lies in supply chain finance. Companies can use an embedded finance platform within their ERP system to manage invoices. AI could analyze invoice data to predict payment behaviors and optimize cash flow. Meanwhile, blockchain could secure the entire transaction history, providing an immutable record for all participants, from suppliers to lenders, enhancing trust and efficiency across the supply chain. This demonstrates how fintech trends banking are creating robust, interconnected ecosystems.
Challenges and Opportunities for US Financial Institutions
While the opportunities presented by these fintech trends banking are immense, there are also significant challenges. Traditional banks face the dual pressure of modernizing legacy systems and competing with agile fintech startups. Regulatory bodies are grappling with how to supervise rapidly evolving technologies while fostering innovation and protecting consumers.
- Legacy Systems: Many established financial institutions are burdened by outdated IT infrastructure, making it difficult to integrate new technologies effectively.
- Talent Gap: There’s a growing demand for skilled professionals proficient in AI, blockchain, and data science, creating a talent gap within the traditional banking sector.
- Regulatory Uncertainty: The rapid pace of technological innovation often outstrips the development of clear regulatory frameworks, creating uncertainty for institutions adopting these technologies.
- Data Privacy and Security: As more data is collected and processed, ensuring robust data privacy and cybersecurity measures becomes paramount to maintain customer trust.
Despite these challenges, the trajectory is clear. Financial institutions that embrace these fintech trends banking innovations and strategically invest in their implementation will be the ones to thrive in the coming years. This often means fostering a culture of innovation, partnering with fintech companies, and prioritizing customer-centric solutions.
Conclusion: Preparing for the Future of US Financial Services
By 2026, the US financial services landscape will be profoundly shaped by the ongoing revolution of fintech. Artificial intelligence, embedded finance, and blockchain technology are not merely incremental improvements; they are fundamental shifts that are redefining how financial services are delivered, consumed, and regulated. These fintech trends banking is adopting promise a future of greater efficiency, enhanced security, hyper-personalization, and unprecedented accessibility.
For consumers, this means more convenient, personalized, and often cheaper financial products and services. For businesses, it translates into streamlined operations, new revenue opportunities, and deeper engagement with their customer base. For financial institutions, it’s a call to action – to innovate, adapt, and collaborate, or risk obsolescence.
The journey towards 2026 will be dynamic, filled with both challenges and immense opportunities. Those who understand and strategically leverage these key fintech trends banking will not only survive but will lead the charge in creating a more efficient, equitable, and intelligent financial future for the United States.